See the NYC housing lotteries open right now →
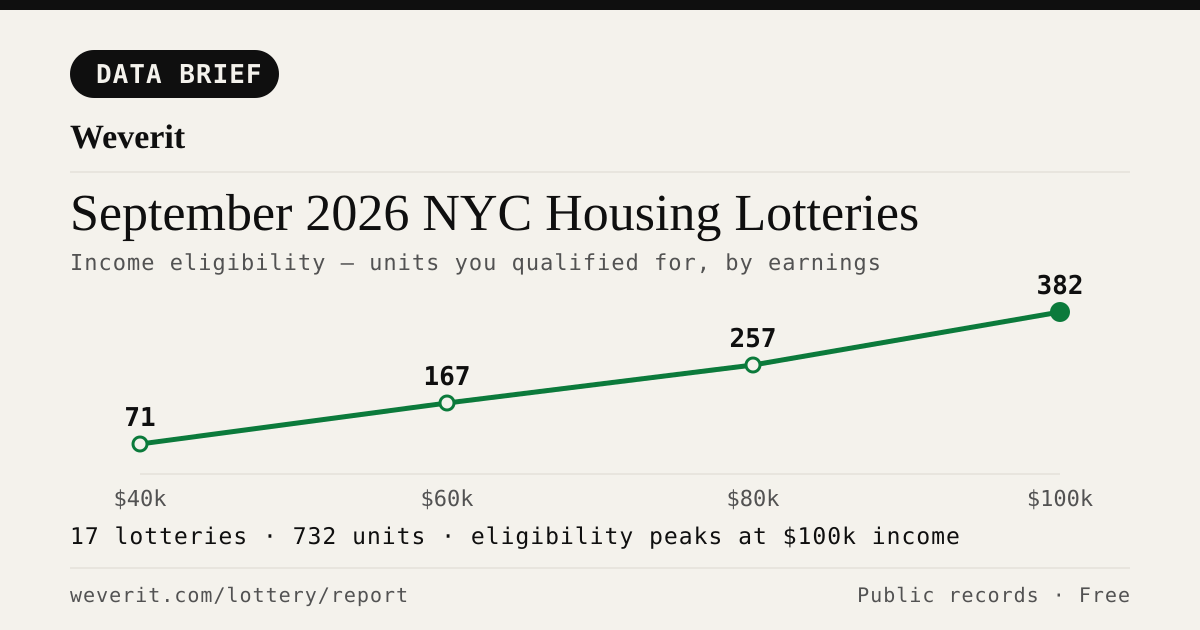
The single most common reason people apply to NYC housing lotteries they can't win: they don't match the income range. Every unit has both a minimum and a maximum income, set by household size and AMI band. Here's how to read those numbers so you only apply where you actually qualify. (New to the lottery overall? Start with how NYC Housing Connect works.)
What AMI means
AMI stands for Area Median Income — the midpoint income for the New York City metropolitan area, published annually by the federal government (HUD) and used by NYC to set affordable housing eligibility. Listings express eligibility as a percentage of AMI: a "50% AMI" unit is aimed at households earning around half the area median, a "130% AMI" unit at households earning well above it.
Affordable lottery units span a wide range — from extremely low income (around 30% AMI) up to middle income (as high as 165% AMI on some developments). That's why the same lottery can have units for very different income levels in the same building.
Why there's both a minimum and a maximum
Every unit lists an income range, not just a ceiling:
- The maximum keeps units going to households within the targeted income level — earn more than the max and you don't qualify for that unit.
- The minimum exists because the rent is fixed; the city wants reasonable assurance you can afford it. Earn less than the minimum and you may not qualify — unless you hold a Section 8 or similar voucher, in which case the minimum often doesn't apply.
So you qualify for a specific unit when your household income lands inside that unit's min–max window — and your household size matches the unit.
How household size changes everything
AMI figures are published per household size. A larger household has a higher AMI dollar figure than a single person at the same AMI percentage, because the income needed to support more people is higher. So the same "80% AMI" band translates to a different dollar range for a household of one versus a household of four.
Household size counts everyone who will live in the apartment, and it also has to fit the unit — a studio and a three-bedroom have different household-size rules. Applying for a unit size that doesn't match your household can lead to disqualification if you're selected.
What counts as income
When you check whether you fall inside a range, count all household income — not just wages:
- Salary, hourly wages, and tips
- Social Security and pensions
- Child support
- Interest from savings and gains from investments
That last point catches people: money sitting in savings or investments generates income that counts, which can push you into a higher AMI band than your salary alone suggests. (Assets themselves are tested separately — see our asset-limits guide.)
How to find your range
- Note your total annual household income (everyone who'll live there, all income sources).
- On a listing, look at the income range for the unit size that matches your household.
- If your income falls between that unit's minimum and maximum, you qualify to apply for it.
- Apply to every lottery and unit where you fit — each is an independent draw.
Because AMI figures update annually and ranges differ by listing, always read the specific lottery's income chart rather than relying on a figure from another building or a previous year.
Frequently asked questions
What income do I need for the NYC housing lottery? It depends on the specific unit — there's no single citywide number. Every lottery unit sets an income range with both a minimum and a maximum, based on your household size and its AMI (Area Median Income) band, and you qualify only when your total household income falls inside that unit's range and your household size fits. Affordable units span a wide spread, from extremely low income (around 30% AMI) up to middle income (as high as 165% AMI on some developments), so the same building can hold units for very different income levels. Count all household income — not just wages — when you check where you fit.
Why is there a minimum income? Because the rent on an affordable unit is fixed, listings set a minimum income to give reasonable assurance you can actually afford it — the range isn't just a ceiling. If your household earns less than that minimum, you may not qualify for the unit. There's an important exception: if you hold a Section 8 or similar voucher, the minimum often doesn't apply, since the voucher covers the affordability gap. The maximum works the other way, keeping units targeted to the intended income level — earn more than the maximum and you don't qualify for that particular unit, though a higher-AMI unit may still fit.
Does household size affect the income limits? Yes — significantly. AMI figures are published per household size, so a larger household has a higher AMI dollar figure than a single person at the same AMI percentage, because supporting more people takes more income. That means the same "80% AMI" band translates into a different dollar range for a household of one versus a household of four. Household size counts everyone who will live in the apartment, and it also has to fit the unit — a studio and a three-bedroom have different household-size rules. Applying for a unit size that doesn't match your household can lead to disqualification if you're selected, so match both the dollars and the unit size.
What income counts? All household income counts, not just your W-2 wages. That includes salary, hourly wages, and tips; Social Security and pensions; child support; and interest from savings plus gains from investments. That last category catches people off guard: money sitting in savings or investments generates income that counts, which can push you into a higher AMI band than your salary alone would suggest. Assets themselves are tested separately under the asset limit, but the income they produce is folded into your household income calculation. So when you check a range, total every source across everyone who will live in the apartment.
Can I be over the income limit and still apply? For a given unit, no — if your household income exceeds that unit's maximum, you don't qualify for it, and applying anyway risks disqualification at review. But "over the limit" is always relative to a specific unit's AMI band, not to the lottery as a whole. Affordable units span a wide range, up to middle income (as high as 165% AMI on some developments), so a household that's over the cap for a 50% AMI unit may fit comfortably inside a higher-AMI unit in the same building or another lottery. Read each listing's chart and apply where your income actually lands.
Related NYC housing guides
- How NYC Housing Connect Works
- Asset Limits for the NYC Housing Lottery, Explained
- How to Apply to the NYC Housing Connect Lottery
Sources: NYC Housing Connect (housingconnect.nyc.gov); NYC HPD; HUD AMI guidance. AMI figures and income ranges update annually and vary by listing — confirm current terms on the official listing. This article is for informational purposes only and is not legal advice.